Bringing Digital Security to the Real Estate Closing Table


Updated August 13, 2026
Digital security for real estate closings is no longer a remote-transaction concern. In-person closings face the same identity risks as remote ones, and they often carry less protection because the assumption of physical presence creates a false sense of certainty.
Key takeaways
- Seller impersonation fraud affected nearly one-third of title companies in 2023, and real estate fraud losses reached $275 million in 2025, a 58% increase.
- In-person closings are just as vulnerable to identity fraud as remote ones. Fake IDs, forged documents, and synthetic identities can pass visual inspection, especially when title agents are managing licenses from all 50 states.
- Layered digital identity verification, including credential analysis, biometric matching, and liveness detection, can be added to in-person closing workflows without slowing down the signing experience.
- The right security posture covers the full closing lifecycle: before the order opens, at check-in, and at the table itself.
Why in-person closings are still vulnerable to identity fraud
Being face-to-face with a signer does not eliminate identity risk. Today's fraudsters use forged government IDs, synthetic identities built from real data fragments, and, increasingly, AI-generated documents that pass visual inspection.
Title agents are expected to recognize valid credentials from all 50 states, each with different formats, barcodes, holograms, and security features. That is an unreasonable burden to place on any individual, and fraudsters know it. A single forged ID can compromise an entire transaction, expose the title company to liability, and damage client relationships that took years to build.
Unlike remote closings, in-person workflows rarely include credential scanning or selfie verification. That gap is exactly where seller impersonation fraud enters.
What seller impersonation fraud looks like in practice
Seller impersonation is the fastest-growing fraud pattern in residential real estate. A fraudster researches a property, obtains or fabricates identity documents matching the owner's name, and presents themselves at closing as the seller. If the title agent relies only on visual ID inspection, the fraud can succeed.
The pattern is especially common in:
- Vacant land and investment properties where the real owner is not actively monitoring the asset
- Out-of-state sellers who are expected to close remotely or through a representative
- Elderly homeowners whose identities are easier to research and replicate
The U.S. Department of Justice charged 11 people in one case involving a conspiracy that used stolen identities to secure millions in hard-money loans against properties the fraudsters had no claim to. That case, and others like it, share a common thread: the identity check at closing was not strong enough to catch the fraud.
How digital identity verification works at an in-person closing
Adding digital identity checks to an in-person closing workflow does not require replacing the signing experience. It requires inserting a short, structured verification step before the signer reaches the table.
With Proof, the process works like this:
- The signer scans a QR code at reception or opens a link sent before the appointment.
- They photograph their government-issued ID and take a quick selfie.
- Proof runs credential analysis across 400-plus signals, including barcodes, document structure, and photo consistency, while simultaneously running biometric matching to confirm the face in the selfie matches the face on the ID.
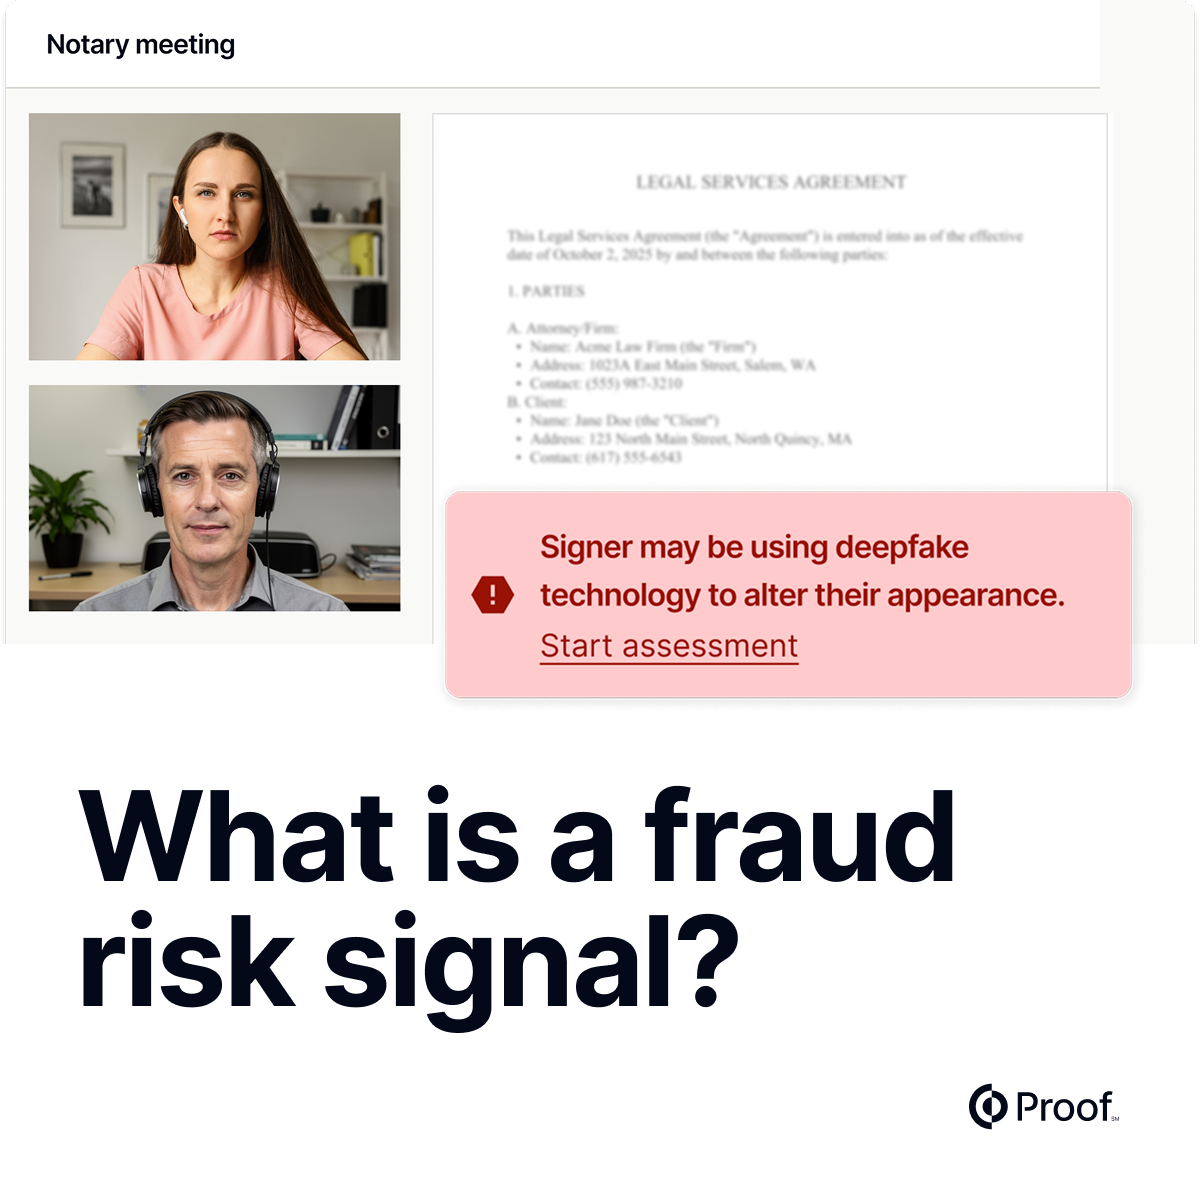
- The system checks for liveness to confirm the selfie is a real person, not a photo or deepfake.
- The title agent receives a complete identity report before the signer reaches the closing table.
The entire process takes a few minutes. The identity report becomes a permanent, audit-ready record tied to the transaction.
What the identity report gives you
The Proof identity report is more than a pass/fail result. It documents every check performed, every signal evaluated, and the outcome of each step. That record matters in two situations.
First, it supports compliance. Title agents, lenders, and real estate attorneys operate under state and federal requirements that increasingly demand documented identity verification. A detailed identity report demonstrates that the organization followed a consistent, defensible process.
Second, it protects you if a transaction is disputed. If a seller impersonation claim surfaces after closing, the identity report shows exactly what was verified, when, and how. That documentation is the difference between a defensible position and a liability exposure.
How to evaluate digital security for your closing workflow
Not all identity verification tools are built to the same standard. When evaluating options for your closing workflow, look for these specific capabilities.
- Credential analysis depth: The system should evaluate more than the visual appearance of an ID. It should check barcodes, document structure, font consistency, and other signals that indicate whether a credential is genuine.
- Biometric matching: The system should compare the face on the ID to the face in the selfie using algorithmic matching, not human judgment.
- Liveness detection: The system should confirm that the selfie is a live person, not a photograph, printed image, or deepfake.
- Audit-ready output: Every verification should produce a documented report that can be stored with the transaction file and produced if the closing is later disputed.
- Workflow flexibility: The tool should support verification at multiple points in the closing process, not just at the moment of signing.
- Compliance certifications: Look for platforms that hold SOC 2 Type II certification and meet NIST Identity Assurance Level 2 (IAL2) standards. These certifications indicate that the identity verification process has been independently validated.
Proof holds SOC 2 Type II, Kantara IAL2, MISMO, and WebTrust certifications. The Proof Engine processes 4.5 million-plus compliance rules to enforce state remote online notarization (RON) standards and underwriter requirements automatically.
Who needs digital identity verification at closings
Digital identity verification at the closing table is relevant to every professional who touches a real estate transaction.
- Title agents carry the most direct exposure. If a fraudulent seller impersonation succeeds, the title company is typically the first line of liability. A documented identity verification process is both a fraud prevention measure and a compliance record.
- Real estate attorneys who conduct closings face the same exposure. In states where attorneys handle closings, the attorney's professional responsibility includes confirming the identity of the parties.
- Lenders have a direct interest in confirming that the borrower who signed the loan documents is the same person who applied. Seller impersonation fraud can result in loans secured against properties the lender has no valid claim to.
- Brokers who refer clients to closing services have a reputational interest in the security of the process. A fraud incident at closing reflects on everyone involved in the transaction.
Securing the full closing lifecycle
Identity fraud does not always happen at the signing table. It can enter the transaction at any point from the initial order through post-closing disbursement. A complete security posture covers each stage.
- Before the order opens: Verify the seller's identity before accepting the listing or opening escrow. A QR code or link sent with the initial engagement request can complete verification before any documents are prepared.
- At check-in: Use the reception desk or waiting area as the verification point. A reusable QR code posted at the front desk allows every signer to complete verification before they enter the closing room.
- At the closing table: For transactions where pre-verification was not completed, Proof supports in-session verification that can be initiated by the title agent or notary.
- Post-closing: The identity report is stored and accessible for the life of the transaction. If a dispute arises months or years later, the verification record is retrievable.
The threats are not slowing down. Real estate fraud losses grew 58% in a single year, and the tools available to fraudsters are improving faster than traditional verification methods can adapt. A layered, documented identity verification process is the most direct response available to title agents, lenders, and attorneys who want to protect their clients and their organizations.